Nigeria's Banking Capital Race: What Recapitalization Really Means for the Economy
26 March 2026
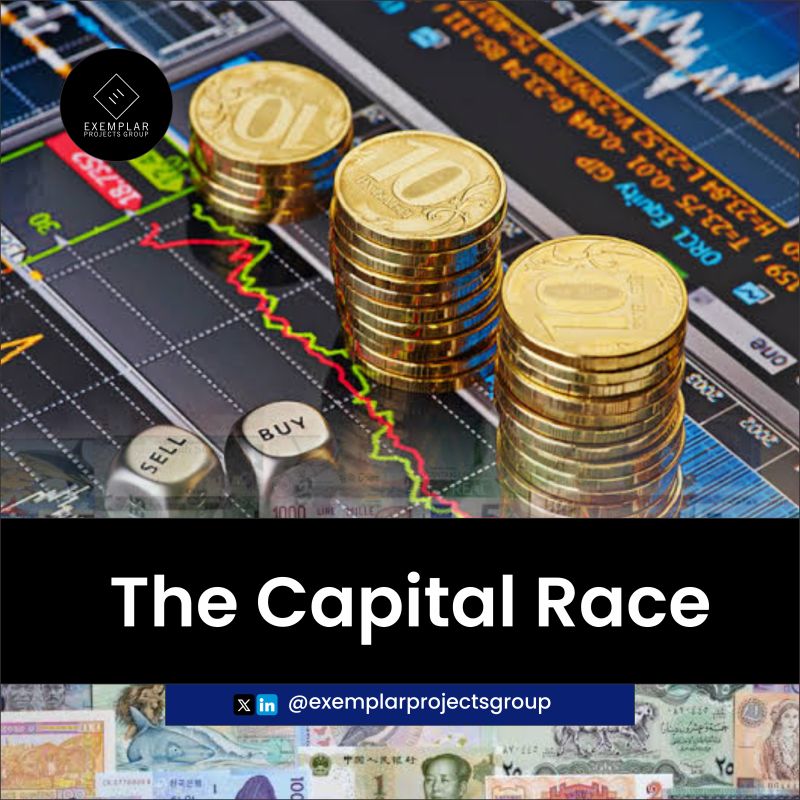
Nigeria's banking industry has entered a defining moment. With the new capital requirements introduced by the Central Bank of Nigeria, banks are now under pressure to significantly increase their capital base within a fixed timeline. The policy is designed to strengthen financial institutions so they can support a larger and more complex economy. Yet beyond the numbers lies a deeper question: what happens to a financial system when the cost of remaining competitive suddenly rises?
Nigeria has seen this story before. In 2004, a sweeping reform led by former CBN governor Charles Soludo raised the minimum capital requirement for banks from ₦2 billion to ₦25 billion. The result was dramatic. The number of banks shrank from 89 to 25 through mergers and acquisitions, creating stronger institutions capable of financing larger projects. Research by the International Monetary Fund later noted that the consolidation significantly improved bank capitalization and resilience, although it also reduced the number of players in the industry.
Today's recapitalization effort could trigger similar dynamics. Larger banks may find it easier to attract investment and expand lending to sectors such as infrastructure, manufacturing, and technology. For example, institutions like Access Bank and Zenith Bank have already demonstrated how stronger capital structures can support international expansion and large-scale financing deals. However, smaller banks may face difficult choices: raise fresh equity, merge with competitors, or risk losing their licenses.
Studies on financial stability provide useful insight into why regulators pursue such reforms. A report by the World Bank on banking sector resilience argues that well-capitalized banks are better positioned to absorb economic shocks, maintain lending during downturns, and protect depositors' funds.
Yet the reform also raises important concerns. What if consolidation leads to fewer banks serving millions of customers? Reduced competition could make credit harder to access for small businesses and emerging entrepreneurs who already struggle to secure financing. Financial inclusion must therefore remain a priority as the sector evolves.
One possible solution lies in balancing strength with diversity. Regulators can encourage tiered banking structures where larger banks handle large-scale financing while smaller institutions focus on niche markets such as small-business lending and digital banking.
Ultimately, the success of this capital race will not be measured simply by how much money banks raise. Its real impact will be determined by whether a stronger banking system translates into broader economic opportunity. If managed carefully, recapitalization could produce banks that are not only bigger but also more capable of financing Nigeria's long-term growth.
More articles
 Finance
8 Mar 2026
The Democratization of Investment: Access, Risk, and the New Wealth Divide
 Business Strategy
22 Sept 2026
Africa Has the Resources, But Who Captures the Value
 Finance
21 Sept 2026
From Consumer to Owner: What the Dangote IPO Could Mean for Nigerians
SWAVE Money
Ready to bank smarter?
Zero-data banking, instant transfers, and real rewards. Download SWAVE Money today.